Home Loan Eligibility and Process for Pre-Launch Apartments
Featured Image of Home Loan Eligibility and Process for Pre-Launch Apartments


You can get a home loan for a pre-launch flat only after RERA registration and bank approval. Before that, you must pay any expression of interest amount from your own savings. Once approved, banks lend up to 75% of the price for homes above ₹75 lakh, under RBI rules. Your eligibility depends on your income, age, credit score and existing loans. The bank then releases the loan in stages as construction moves ahead.
Why Banks Wait for RERA Approval


Banks lend only on projects with clear title, approved plans and RERA registration. At the pre-launch stage, these approvals are still in process. So banks cannot yet check the project or sign a tie-up with the builder.

Most large builders get their projects pre-approved by major banks soon after launch. This approval speeds up your loan, since the bank has already checked the project's legal papers.

RBI Loan-to-Value Limits


The RBI sets how much a bank can lend against a home's value.

Home Loan Amount Maximum Funding
Up to ₹30 lakh 90% of the property value
₹30 lakh to ₹75 lakh 80% of the property value
Above ₹75 lakh 75% of the property value

For premium homes in Mumbai, you will fall in the last group. So plan to pay at least 25% of the price yourself, plus stamp duty and registration.

What Decides Your Eligibility


Factor What Banks Check
Income Salary slips, tax returns or business income
Age Most banks want the loan closed by age 60 to 70
Credit Score A score above 750 gets the best rates
Existing EMIs Total EMIs should stay within 40% to 50% of income
Job Stability Years in current job or business
Co-Applicant A working spouse can raise your loan amount

How Much Loan Can You Get?


Here is a rough guide at 7.5% for 20 years, with EMIs at 50% of take-home pay.

Monthly Take-Home Pay Max EMI at 50% Approx. Loan Eligibility
₹2.5 lakh ₹1.25 lakh About ₹1.55 Cr
₹3.5 lakh ₹1.75 lakh About ₹2.17 Cr
₹5 lakh ₹2.50 lakh About ₹3.10 Cr
₹7 lakh ₹3.50 lakh About ₹4.34 Cr

Actual eligibility varies by bank, rate and your credit profile.

Step-by-Step Loan Process for Pre-Launch Homes


  • Check your eligibility with two or three banks before you book.
  • Pay the expression of interest amount from your own funds.
  • Wait for the project's RERA registration and official launch.
  • Pay the booking amount and sign the Agreement for Sale.
  • Pay stamp duty and register the agreement at the sub-registrar's office.
  • Apply for the loan with the bank that has approved the project.
  • Submit your documents and complete the bank's checks.
  • Receive the sanction letter with rate, tenure and terms.
  • The bank pays the builder in stages as construction progresses.

Documents You Need


  • PAN card and Aadhaar card for identity and address proof.
  • Salary slips for three to six months, or business income proof.
  • Income tax returns for the last two to three years.
  • Bank statements for the last six months from your salary account.
  • Booking receipt and the registered Agreement for Sale with the builder.
  • The builder's demand letter for each payment stage as work moves ahead.
Pre-EMI or Full EMI During Construction


Your bank pays the builder in stages, so your loan grows over time. You can choose how to repay during this period.
  • Pre-EMI means you pay only interest on the amount released so far.
  • Full EMI means you pay principal and interest from the first release.

Pre-EMI keeps early payments low, which helps if you pay rent at the same time. Full EMI closes your loan sooner and cuts total interest.

Tax Benefits on Your Home Loan


Under the old tax regime, you can claim tax benefits once you get possession.

  • Up to ₹2 lakh a year on interest for a self-occupied home.
  • Up to ₹1.5 lakh a year on principal under Section 80C.
  • Interest you pay during construction, spread over five years after possession.

The new tax regime does not allow these benefits on a self-occupied home. Speak to a tax advisor to choose the right regime.

Example: Planning a Loan for a Borivali Pre-Launch Home


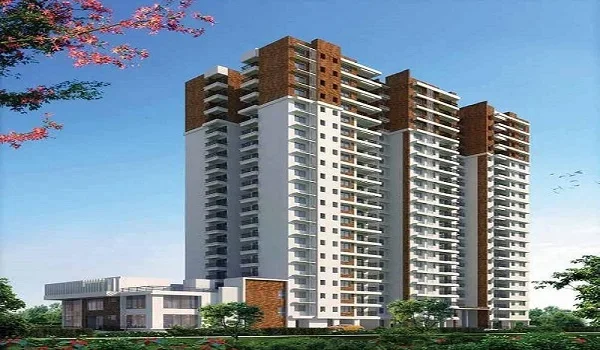
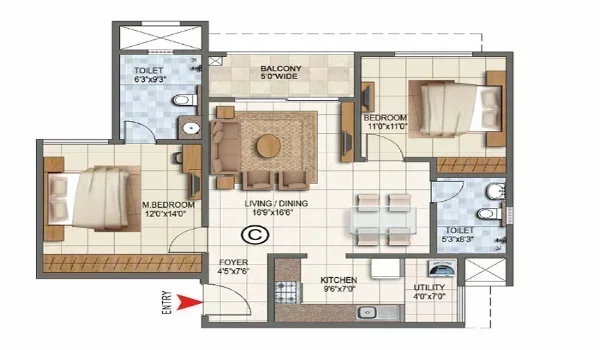
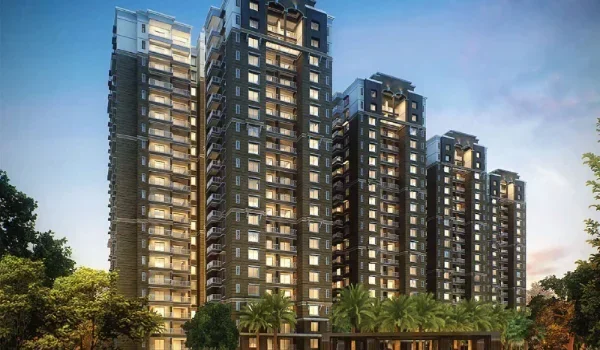
Take a 2 BHK at Prestige Grove Park priced at about ₹2.55 Cr. Under RBI limits, the bank can fund up to 75%, or about ₹1.91 Cr. At 7.5% for 20 years, your EMI would be about ₹1.54 lakh a month.

You need to arrange about ₹63.75 lakh as your own contribution, plus ₹15.30 lakh in stamp duty. The project plans to launch in March 2027, so you have time to prepare these funds.

FAQs


1. Can you get a home loan for a pre-launch apartment?

No, banks lend only after the project gets RERA registration and approval. You must pay any pre-launch amount from your own funds. Once approved, you can apply for the loan as normal.

2. How much loan can you get for a ₹2.5 Cr flat?

For homes above ₹75 lakh, RBI rules cap the loan at 75% of the value. So on a ₹2.5 Cr flat, you can borrow up to about ₹1.875 Cr. Your income and credit score also decide the final amount.

3. What credit score do you need for a home loan?

A credit score above 750 helps you get the best rates and quick approval. Scores between 650 and 750 may still qualify at higher rates, so clear old dues before you apply.

4. When does the bank release the home loan for an under-construction flat?

The bank pays the builder in stages as construction reaches set milestones, based on each demand letter. Your EMI or pre-EMI grows with each release.

5. Can you claim tax benefits on a home loan for an under-construction flat?

You can claim benefits under the old tax regime only after possession. Interest paid during construction gets spread over five years from then. The new regime does not allow these benefits on self-occupied homes.

6. Does a co-applicant increase home loan eligibility?

Yes, adding a working spouse or parent as co-applicant raises your combined income and your loan amount. A woman co-owner may also help you save on stamp duty in Maharashtra.

Prestige Grove Park Blog


Enquiry
Enquire Now